SME SRF Loan 2026: Who Qualifies, Rates and 2027 SME Tax
SME SRF Loan 2026: Who Qualifies, Rates and 2027 SME Tax
BNM’s SME Stabilisation Relief Facility offers viable SMEs hit by the Middle East conflict up to RM750,000 in working capital at up to 3.75% a year with no collateral until 30 June 2027. Here is who qualifies, how to apply and what the Budget 2027 SME tax proposals mean.
By FinDoctor Malaysia · Last updated
Content
SME SRF Loan 2026: Who Qualifies, Rates and 2027 SME Tax
Quick answer: The SME SRF loan, BNM’s SME Stabilisation Relief Facility, offers viable Malaysian SMEs hit by the Middle East conflict up to RM750,000 in working capital at up to 3.75% a year, with no collateral. It runs until 30 June 2027 or until the RM10 billion fund is used up. You apply through a participating bank, and each bank decides case by case.
What is the SME SRF?
The SME SRF is a RM10 billion targeted relief facility under Bank Negara Malaysia’s Fund for SMEs. It provides short-term working capital to small and medium enterprises, including microenterprises, that are viable but materially affected by the geopolitical conflict in the Middle East, which began in March 2026.
By 30 September 2026, RM3.8 billion had been approved for more than 6,800 SME accounts under the facility’s initial RM5 billion allocation, according to a joint statement by the banking industry associations reported by The Star. Budget 2027 added another RM5 billion, bringing the total to RM10 billion.
Who is eligible for the SME SRF?
- Malaysian SMEs and microenterprises with at least 51% Malaysian shareholding or ownership, as defined under the national SME definition guideline.
- Viable businesses materially affected by trade and supply chain disruptions from the Middle East conflict. Banks look at the nature of your business and the impact on your cash flow and liquidity buffers, your costs and margins, and your revenue.
- New and existing customers. You do not need to bank with the institution already.
Each participating financial institution assesses applications case by case, including whether your business counts as materially affected.
What is the SME SRF interest rate and tenure?
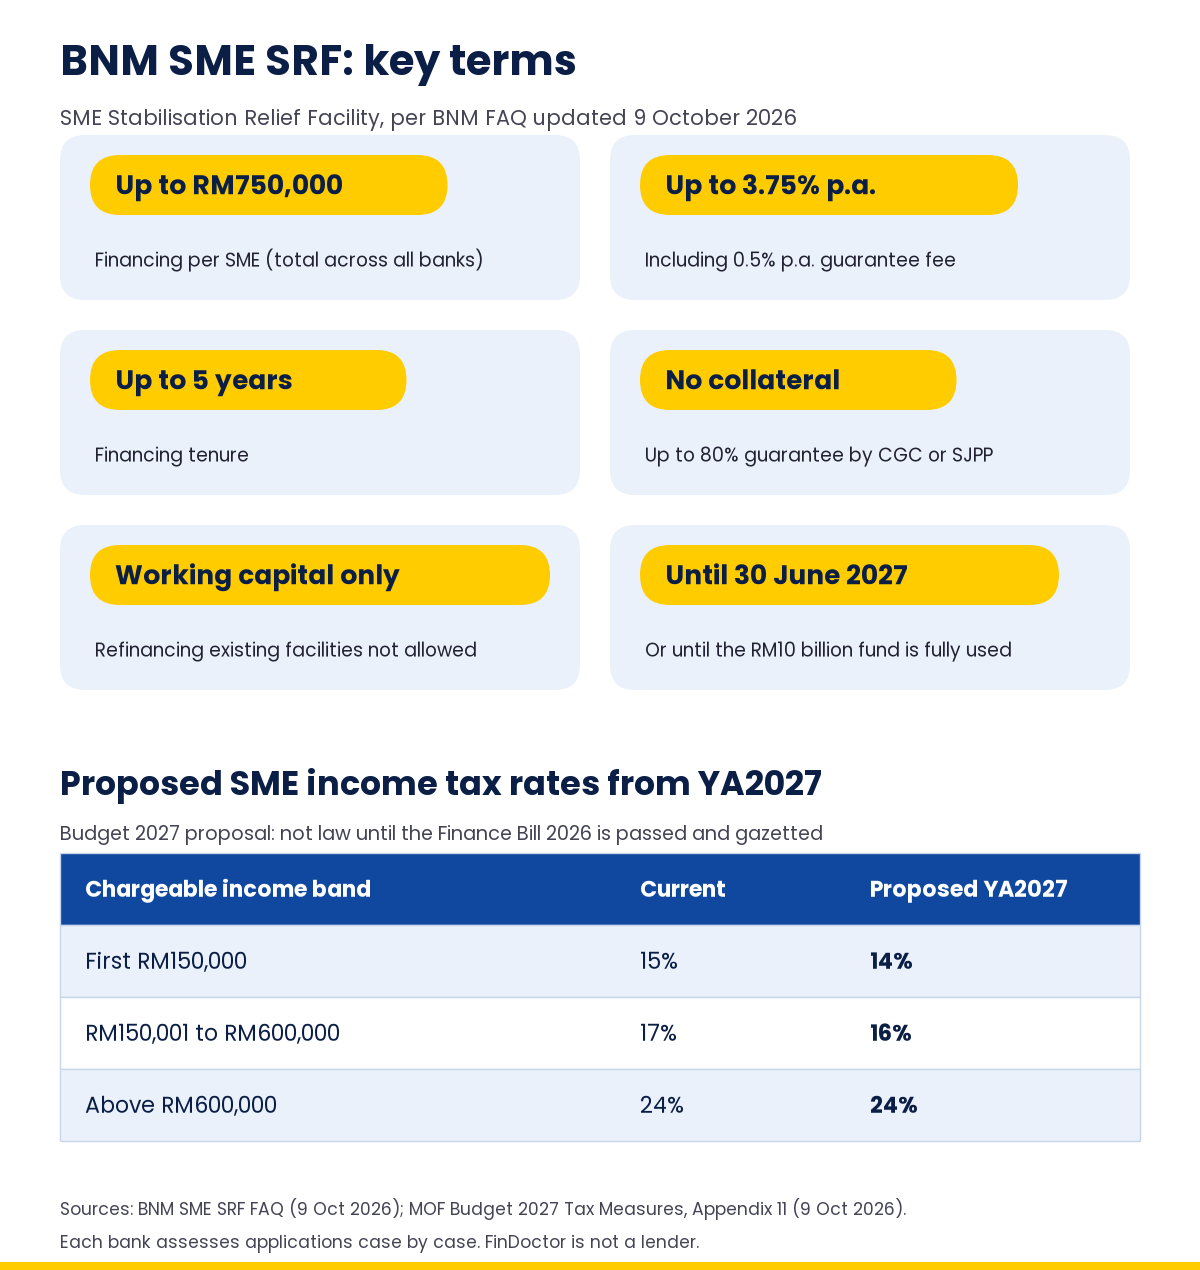
SME SRF financing is capped at RM750,000 per SME at up to 3.75% p.a. including a 0.5% guarantee fee.
| Feature | SME SRF term |
|---|---|
| Financing amount | Up to RM750,000 per SME (total across all banks) |
| Financing rate | Up to 3.75% p.a., including a 0.5% p.a. guarantee fee |
| Tenure | Up to 5 years |
| Guarantee | Up to 80% from Credit Guarantee Corporation Malaysia (CGC) or Syarikat Jaminan Pembiayaan Perniagaan (SJPP) |
| Collateral | Not required |
| Purpose | Working capital only. Refinancing existing facilities is not allowed |
| Availability | Until 30 June 2027 or full use of the RM10 billion, whichever is earlier |
Related SMEs with common shareholding each have their own RM750,000 limit, provided they employ separate workforces.
The SJPP tranche has extra conditions. The government guarantee tranche run by SJPP (GGSM4-SRF) has a RM2.5 billion limit. It requires at least 3 years in business, or 2 to 3 years if the key person has at least 3 years of experience in a similar business. The 0.5% guarantee fee is payable upfront, and applications close on 31 December 2026 or when the limit is used, whichever is earlier.
How do I apply for an SME SRF loan, and what documents do I need?
- Contact a participating financial institution. These are commercial banks, Islamic banks and development financial institutions regulated by BNM. The list is on BNM’s Fund for SMEs page.
- Show a viable track record. Banks may ask for bank statements and transaction records, your CCRIS account conduct, and audited financial statements or management accounts.
- Show the impact on your business. Banks may ask for sales records, invoices and purchase orders, supplier contracts or correspondence showing cost increases, delays or cancellations, and stock movement or debtor and creditor ageing reports.
Banks will strive to decide within 7 business days of receiving complete documents. If one bank declines, you may apply to another.
What changes for SME tax in 2027?
From YA2027 the SME tax rate on the first RM150,000 of chargeable income is proposed to fall from 15% to 14%. The rate applies to companies with paid-up ordinary share capital of RM2.5 million or less, and to limited liability partnerships with capital contributions of RM2.5 million or less, with annual sales of up to RM50 million.
| Chargeable income band | Current rate | Proposed from YA2027 |
|---|---|---|
| First RM150,000 | 15% | 14% |
| RM150,001 to RM600,000 | 17% | 16% |
| Above RM600,000 | 24% | 24% |
Illustrative savings, based on the MOF rate table and ignoring other reliefs and incentives:
| Chargeable income | Tax at current rates | Tax at proposed rates | Saving |
|---|---|---|---|
| RM150,000 | RM22,500 | RM21,000 | RM1,500 |
| RM400,000 | RM65,000 | RM61,000 | RM4,000 |
| RM600,000 | RM99,000 | RM93,000 | RM6,000 |
The maximum saving is RM6,000 a year, reached at RM600,000 of chargeable income. Two other Budget 2027 proposals matter for SMEs:
- Small value assets: the per-asset limit for full capital allowance rises from RM2,000 to RM3,000 from YA2027. SMEs already have no overall annual cap on these claims.
- Peer-to-peer financing: stamp duty above RM10 would be remitted on P2P loan or financing agreements between SMEs and investors signed from 1 January 2027 to 31 December 2030. The current full exemption ends on 31 December 2026.
These tax measures are proposals. The Finance Bill 2026 was tabled for first reading on 16 November 2026, and they apply only once it is passed and gazetted.
Not eligible? Other options BNM lists
- Talk to your bank early about repayment flexibility, restructuring or rescheduling if you already have financing and expect difficulties.
- AKPK (Agensi Kaunseling dan Pengurusan Kredit) offers the Small Debt Resolution Scheme for SMEs and the Debt Management Programme for individuals and sole proprietors.
- Other BNM and CGC financing: the BNM-CGC Guarantee Scheme for longer-term growth financing, Skim Pembiayaan Mikro for microfinancing and the PENJANA Tourism Financing Facility for tourism SMEs.
- imSME, CGC’s online platform for browsing and applying for SME financing from multiple institutions.
For quicker funding needs, see our guide to fast approval business loans in Malaysia.
How FinDoctor helps
Banks look at your CCRIS account conduct when you apply. Get your free FinDoctor Lite Report to review your credit profile or book Pro Advisory for help preparing a business financing application. FinDoctor is not a lender and does not guarantee approval.
The Lite Report shows how your profile matches against 20 Malaysian banks, and Pro Advisory costs RM650. You can also compare commercial loan options, or check whether commercial refinancing suits existing facilities, since SME SRF cannot be used to refinance.
Frequently asked questions
Can I use an SME SRF loan to refinance an existing loan?
No. BNM says SME SRF financing is strictly for working capital and refinancing of existing credit facilities is not allowed.
Can I apply for SME SRF at more than one bank?
Yes. You may apply to several participating financial institutions but the total approved across all of them is capped at RM750000 per SME.
Do I need collateral for SME SRF?
No. Because the financing carries a guarantee of up to 80% from CGC or SJPP the participating institutions will not ask for collateral.
When does SME SRF close?
The facility is available until 30 June 2027 or until the RM10 billion allocation is fully used. The SJPP guaranteed tranche accepts applications until 31 December 2026 or until its RM2.5 billion limit is used.
What is the SME tax rate in 2027?
Under the Budget 2027 proposal the rate on the first RM150000 of chargeable income falls from 15% to 14% and the rate on RM150001 to RM600000 falls from 17% to 16%. It applies from YA2027 once the Finance Bill 2026 is passed and gazetted.
Sources
- Bank Negara Malaysia, SME SRF Frequently Asked Questions, latest update 9 October 2026
- The Star (Bernama), RM3.8bil financing approved to benefit about 6,800 SME accounts, 28 October 2026
- SJPP, Skim Jaminan Kerajaan MADANI 2026 – BNM SRF (GGSM4 SRF) (accessed 20 November 2026)
- Ministry of Finance, Budget 2027 Tax Measures, Appendices 11, 12 and 21, 9 October 2026
- The Star, Finance Bill proposes lower rates for small businesses, 16 November 2026
- Business Today, Two Finance Bills tabled for first reading, 16 November 2026
This article is general information, not financial or tax advice.
Last updated: 20 November 2026
Apply Now to Get Started!
Get your personalised recommendations on which bank offers the best interest rates for you!
FinDoctor Money Tips

· FinDoc Editorial Team
Malaysia Housing Loan Approval Rate 2026: Why It’s Falling
BNM data shows Malaysian banks approved about 38% of the value of residential property loans applied for in January to September 2026, down from about 41% a year earlier. Here is what the approval ratio means and how to check your readiness before you apply.

· FinDoc Editorial Team
Open Finance Malaysia: What BNM’s New Rules Mean for You
BNM’s Open Finance Policy Document lets you share your bank, e-money and card data between financial institutions, only with your consent. Here is the 2028 to 2030 rollout and what it could mean for loan applications.