
OPR Decision 5 Nov 2026: What a Hold or Hike Means for Your Loans
OPR Decision 5 Nov 2026: What a Hold or Hike Means for Your Loans
Bank Negara decides the OPR on 5 Nov 2026 at 3pm. 8 of 9 economists expect a hold at 2.75%. See what a hold or a 0.25% hike means for your loan instalments.
By FinDoctor Malaysia · Last updated
Content
By FinDoctor Editorial Team · Last updated 3 Nov 2026
Update: Bank Negara Malaysia announces its decision at 3pm on Thursday, 5 Nov 2026. We’ll refresh this article after the announcement.
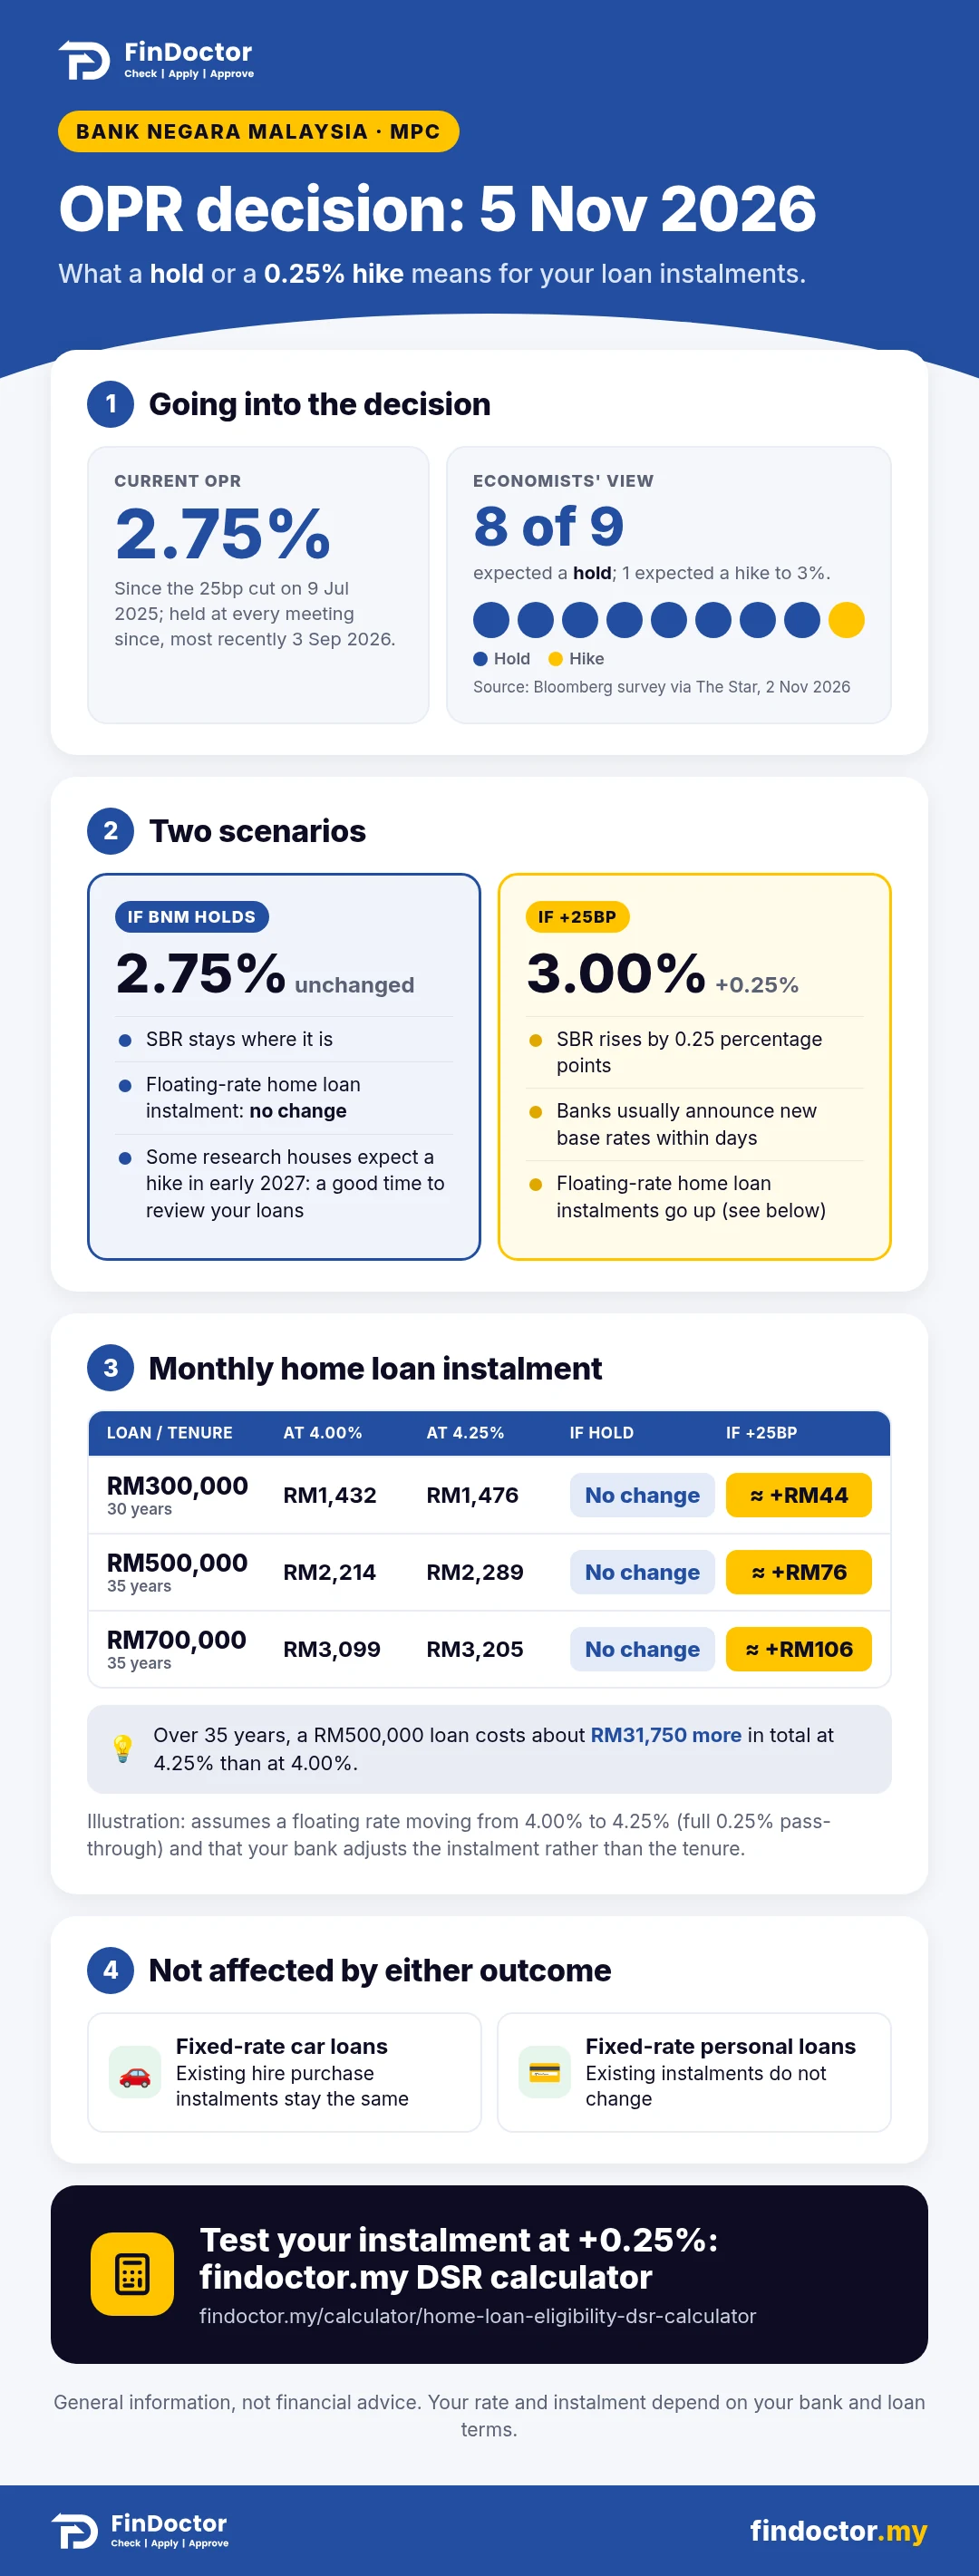
Quick answer: Bank Negara Malaysia (BNM) decides the OPR on Thu 5 Nov 2026 at 3pm. The OPR is 2.75% today, and 8 of 9 economists in a Bloomberg survey expect a hold. If BNM holds, floating-rate instalments stay the same. If it hikes 0.25% to 3.00%, a RM500,000, 35-year home loan would cost about RM76 more a month.
Key takeaways
- Current OPR: 2.75%, unchanged since BNM cut it on 9 Jul 2025.
- Decision: Thursday 5 Nov 2026, 3pm, the last Monetary Policy Committee (MPC) meeting of 2026.
- Expectations: 8 of 9 economists expect a hold; UOB expects a hike to 3.00% (The Star, 2 Nov 2026).
- Who is affected: mainly floating-rate home loans. Most car and personal loans are fixed rate.
When is the next OPR announcement?
BNM’s MPC meets on Thursday, 5 November 2026 and releases its Monetary Policy Statement at 3:00pm, according to the BNM MPC meeting schedule. It is the sixth and final meeting of 2026. BNM usually publishes the next year’s meeting dates in its November statement.
What is the OPR now, and how did we get here?
- BNM cut the Overnight Policy Rate (OPR) by 0.25 percentage points, from 3.00% to 2.75%, on 9 July 2025.
- It has held at 2.75% since, most recently on 3 September 2026. In that statement, BNM said it would stay vigilant to cost pressures and domestic demand.
- Headline inflation was 1.8% in September 2026, with core inflation at 1.7% (The Edge Malaysia, 19 Oct 2026).
Will Bank Negara raise the OPR on 5 November 2026?
Most economists think not. The Star (2 Nov 2026) reported that a Bloomberg survey showed eight of nine economists expect BNM to hold the OPR at 2.75%, while one expects a 0.25-point hike to 3.00%.
- Expecting a hold: CIMB Research and Kenanga Research. CIMB forecasts a hike in March 2027 instead.
- Expecting a hike: UOB, citing BNM’s change in policy guidance in September, stronger-than-expected third-quarter growth and the expansionary Budget 2027.
This is a forecast, not a result. The decision is BNM’s alone, and it is announced at 3pm on 5 Nov.
What does a hold or a hike mean for my loans?
| If BNM holds at 2.75% | If BNM hikes to 3.00% | |
|---|---|---|
| Standardised Base Rate (SBR) | No change | Rises by 0.25 percentage points |
| Floating-rate home loan | Instalment stays the same | Instalment likely rises after your bank revises its rates |
| Existing fixed-rate car loan | No change | No change |
| Existing fixed-rate personal loan | No change | No change |
| New loan applications | Pricing broadly unchanged | New loans may be priced higher |
How much more would my home loan instalment be if the OPR rises?
These examples assume your rate moves from 4.00% to 4.25%, a full 0.25% pass-through, and that your bank adjusts the instalment rather than the tenure.
| Loan amount | Tenure | Hold (4.00%) | Hike (4.25%) | Extra per month |
|---|---|---|---|---|
| RM300,000 | 30 years | RM1,432 | RM1,476 | about RM44 |
| RM500,000 | 35 years | RM2,214 | RM2,289 | about RM76 |
| RM700,000 | 35 years | RM3,099 | RM3,205 | about RM106 |
Over a full 35-year tenure, the RM500,000 loan would cost about RM31,750 more in total at 4.25% than at 4.00%. Some banks keep the instalment and change the tenure instead, so check your bank’s notice.
How does the OPR reach my loan rate?
The OPR is the rate BNM sets for overnight lending between banks. Since 1 August 2022, new retail floating-rate loans and refinancing use the Standardised Base Rate (SBR), which is linked only to the OPR. Your rate is the SBR plus your bank’s spread (BNM Consumer Guide). Older loans use the bank’s Base Rate (BR) or Base Lending Rate (BLR), which banks usually, but not always, adjust by the same amount.
Car and personal loans
Most car loans in Malaysia are fixed-rate hire purchase loans, and most personal loans are fixed rate too. An OPR change does not alter an existing fixed instalment. To compare new offers fairly, use the Flat and Effective Interest Rate Calculator. Thinking of settling early? The Car and Personal Loan Settlement Calculator shows your settlement amount and rebate.
What should borrowers do before 5 November?
- Stress-test your DSR. Run your instalment at today’s rate and at 0.25% higher in the Loan & DSR Calculator.
- Review your home loan spread. If your loan is a few years old, compare it with today’s offers on our home refinancing page. Weigh the savings against legal fees, stamp duty, valuation and any lock-in penalty.
- Clear high-interest debt first. Credit card balances cost far more than a 0.25% rate change.
- Check your credit report. CCRIS and CTOS records affect approval and pricing. A FinDoctor Pro Report gives loan eligibility guidance across the top 20 banks, and a FinDoctor Pro Advisory session offers one-on-one help.
Frequently asked questions
What time does Bank Negara announce the OPR decision on 5 November 2026?
Bank Negara Malaysia releases its Monetary Policy Statement at 3:00pm Malaysia time on Thursday, 5 November 2026, after the final MPC meeting of the year.
What is the current OPR in Malaysia?
The OPR is 2.75%. Bank Negara Malaysia cut it from 3.00% on 9 July 2025 and has held it at every meeting since, most recently on 3 September 2026.
Do economists expect an OPR hike in November 2026?
Mostly not. A Bloomberg survey reported by The Star on 2 November 2026 found eight of nine economists expect a hold at 2.75%. UOB expects a 0.25-point hike to 3.00%.
How much will my home loan instalment increase if the OPR goes up 0.25%?
With full pass-through from 4.00% to 4.25%, a RM300,000 30-year loan rises about RM44 a month, a RM500,000 35-year loan about RM76, and a RM700,000 35-year loan about RM106.
Does the OPR affect my existing car loan?
Usually not. Most Malaysian car loans are fixed-rate hire purchase loans, so the instalment stays the same for the whole tenure regardless of OPR changes.
What is the difference between the SBR and the BR?
The Standardised Base Rate (SBR) is linked only to the OPR and is used for new retail floating-rate loans from 1 August 2022. The Base Rate (BR) is set by each bank and applies to most older loans.
This is general information, not financial advice. Instalment examples are illustrations; your actual rate and instalment depend on your bank and loan terms.
Sources
- Bank Negara Malaysia, MPC Meeting Decision Schedule 2026
- Bank Negara Malaysia, Monetary Policy Statement (3 Sep 2026)
- Bank Negara Malaysia, Monetary Policy Statement (9 Jul 2025)
- Bank Negara Malaysia, Consumer Guide on the Revised Reference Rate Framework (SBR)
- The Star, "The Week Ahead" (2 Nov 2026)
- The Edge Malaysia, "Softer September inflation supports OPR hold, but economists split on hike timing" (19 Oct 2026)
- The Edge Malaysia, "The Week Ahead: All eyes on Bank Negara’s OPR decision" (Nov 2026)

Apply Now to Get Started!
Get your personalised recommendations on which bank offers the best interest rates for you!
FinDoctor Money Tips

· FinDoc Editorial Team
Budget 2027 Stamp Duty for First Homes: What You Could Save
Budget 2027 proposes full stamp duty relief on first homes up to RM500k and 50% relief up to RM750k for SPAs signed 2027–2030. See who qualifies and savings.

· FinDoc Editorial Team
Gen Z Malaysia: Credit Scores Over Savings?
Explore why Malaysian Gen Zs are focusing on credit health over cash savings, plus tips to check your CTOS/CCRIS report.
